Introduction
Bard Santner, a financial services group offering asset management, corporate finance, and remittance solutions, has taken a strategic step into formal banking with a new deposit-taking microfinance licence effective October 2026. The move positions the firm to capture a share of Zimbabwe's $2.45 billion diaspora remittance market.
What Happened
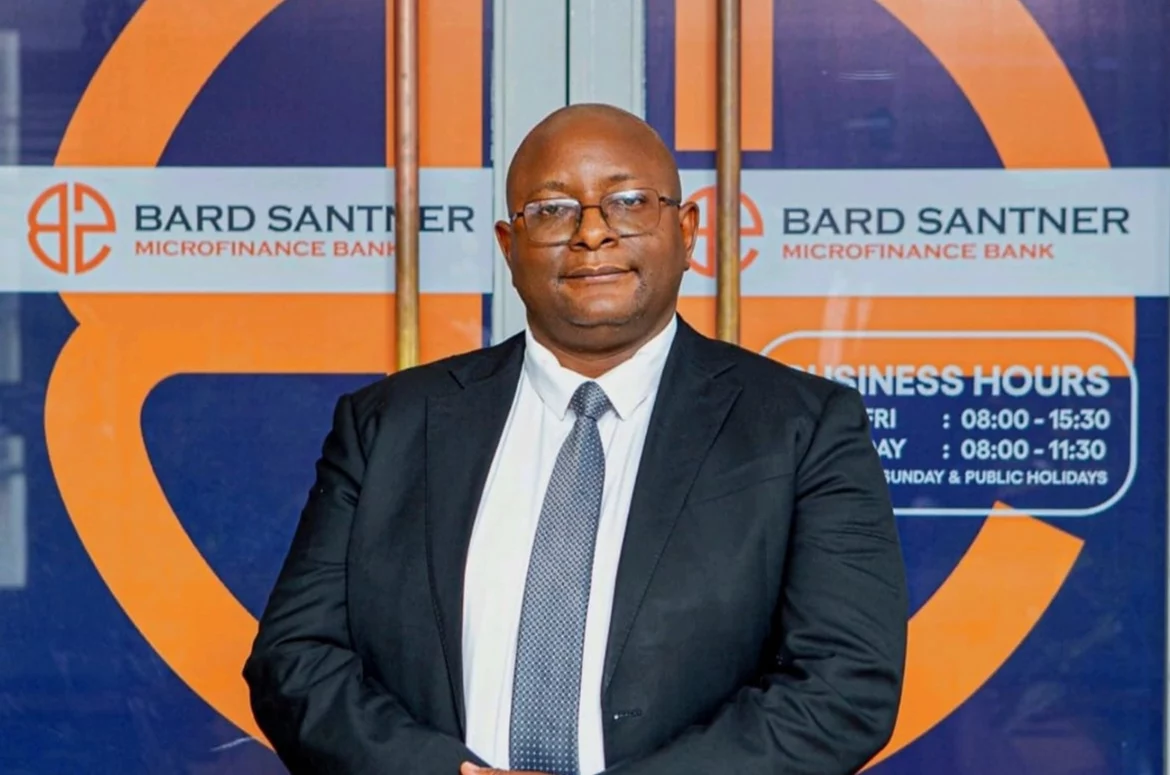
Ngonidzashe Chikowore, managing director of Bard Santner Microfinance Bank, now holds a licence allowing the institution to accept deposits, extend credit and offer savings products. The expansion marks a structural shift from zero-margin transactional transfers to higher-value financial services, including wealth management and lending, built on existing cross-border flows.
Why This Matters
Pure-play remittance operators face intense price compression, but by bundling credit and savings onto every transfer, Bard Santner aims to turn one-time users into long-term banking clients. The strategy hinges on customer lifetime value rather than per-transaction fees. However, the expansion encounters regulatory hurdles in neighbouring South Africa and stiff competition from established digital banks already active in the region.
Key Takeaways
- Licence granted: Bard Santner Microfinance Bank received approval on 1 October 2026 to operate as a deposit-taking institution.
- Market size: The Zimbabwe diaspora remittance market is valued at approximately $2.45 billion, representing a significant untapped resource for formal banking.
- Business model shift: Moving beyond fee-free transfers to integrated lending and savings products increases customer lifetime value.
- Competitive landscape: Regulatory barriers in South Africa and rivalry from incumbent digital banks pose challenges to adoption.
- Long-term vision: The firm aims to convert transactional remittance users into sustained banking clients through bundled financial products.
Conclusion
Bard Santner's expansion into licensed banking represents a bold reimagining of how diaspora remittances can function as a gateway to broader financial inclusion. If successful, the model could reshape how African fintechs monetise cross-border flows, turning every transfer into a potential long-term customer relationship.



Discussion
Join the conversation
Thoughtful reactions, questions, and follow-up ideas help shape the next story.