Introduction
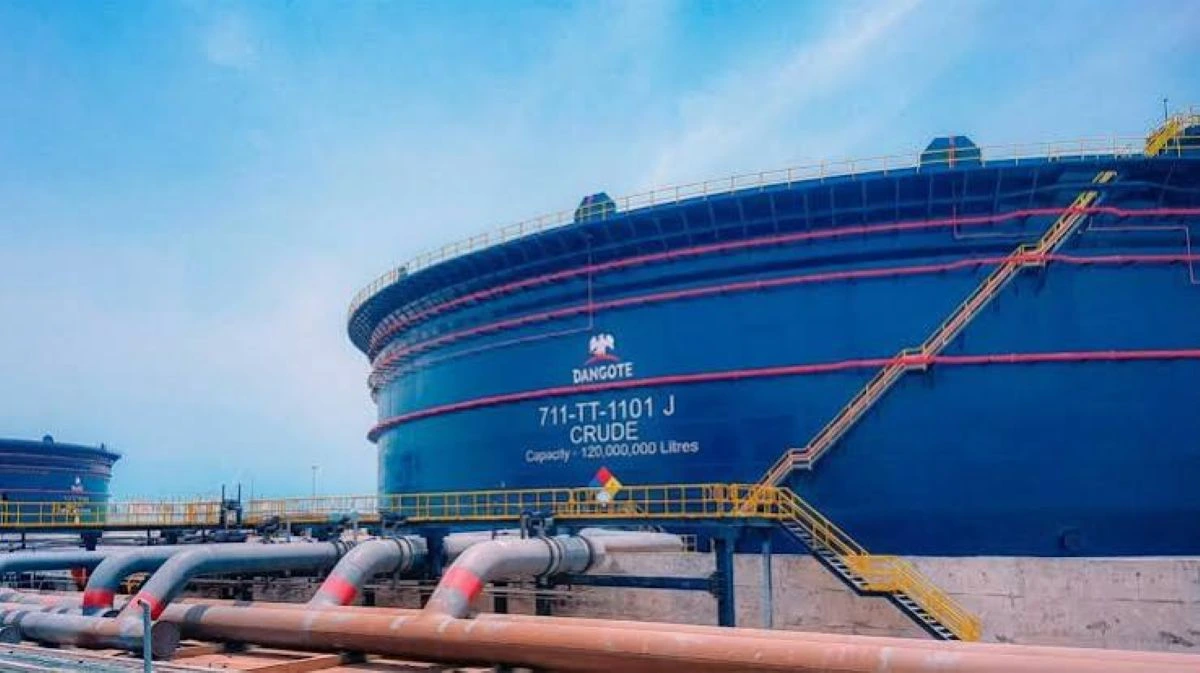
Renaissance Capital has revised its Dangote Petroleum Refinery valuation upward to N700.41 per share, reflecting stronger-than-expected financial performance and a significant premium over the original IPO price. The update underscores the refinery's improved operational trajectory and market position.
What Happened
The investment firm raised its per-share estimate following the refinery's nine-month results through September 2026, which showed net profit jumping to $4.73 billion from a $117.2 million loss in the same 2025 period. Revenue climbed 144.5% year-on-year to $22.48 billion, while EBITDA surged to $5.52 billion from $627.6 million, driven by sharp refining margin expansion across key markets. These results pushed RCA's valuation 13.1% higher than its earlier estimate and established a 33.4% premium to the N525 offer price.
Why This Matters
The valuation lift matters because it signals renewed confidence in Africa's largest refinery at a time when refining margins have tightened globally yet Dangote Refinery has outperformed expectations. RCA notes the upgrade reflects not only stronger 2026 results but also the company's improved cash position, turning net debt into net cash, and adjustments to exchange-rate and discount-rate assumptions. The refinery's valuation also trades at a premium to regional peers, supported by low operating costs and scale advantages, though risks remain around margin sustainability, tax policy, and foreign-exchange movements.
Key Takeaways
- Valuation raised to N700.41 per share, a 33.4% premium to the N525 IPO price
- Nine-month net profit reached $4.73 billion, reversing a prior-year loss
- Revenue grew 144.5% to $22.48 billion, exceeding forecasts
- EBITDA climbed to $5.52 billion, with margin expanding to 24.6%
- Refinery shifted from net debt of $1.73 billion to net cash of $650.8 million
- RCA raised full-year 2026 forecasts for gross refining margin, revenue, and EBITDA
- Second train commissioning could push per-share valuation above N730 if timed as expected
- Key risks include refining margin volatility, taxation, and naira exchange-rate sensitivity
Conclusion
Renaissance Capital's upward revision of the Dangote Refinery valuation to N700.41 per share reflects a convergence of stronger earnings, improved cash flow, and favorable margin dynamics in the third quarter. As the refinery moves toward its expansion timeline, the updated valuation provides a fresh benchmark for investors tracking Nigeria's downstream sector. Stakeholders should monitor margin sustainability, tax policy changes, and forex developments as key drivers of future value.




Discussion
Join the conversation
Thoughtful reactions, questions, and follow-up ideas help shape the next story.