Introduction
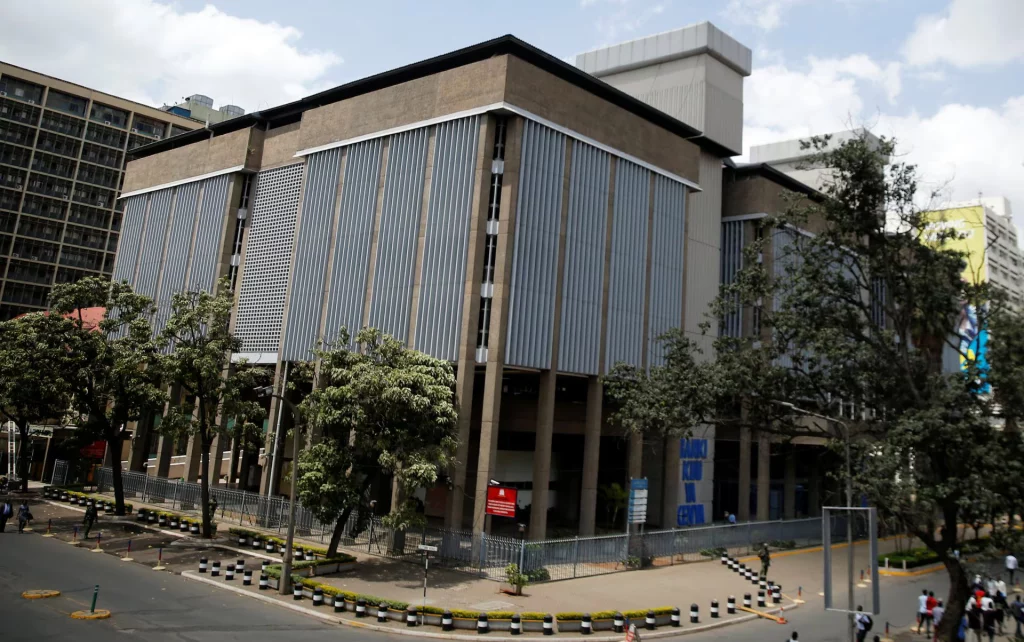
The Central Bank of Kenya is proposing new regulatory authority that could allow it to take control of struggling payment providers before they collapse. The draft National Payment System Bill, 2026 aims to protect customer money and maintain financial stability in a sector where private companies handle growing volumes of digital transactions.
What Happened
CBK officials have outlined powers to intervene when a payment service provider fails to meet customer obligations, breaches regulatory requirements, or threatens overall financial stability. The proposed bill would enable the regulator to appoint a statutory manager, remove responsible officials, and even sell the provider's business to preserve value for creditors and users.
Historical context shows the regulator has acted before: in 2021, CBK revoked Mobile Pay's authorization after it failed to submit required audited accounts and security reports, putting customer funds at risk. The new framework builds on those precedents with a more detailed statutory management regime.
Why This Matters
Payment providers hold and move money for millions of Kenyans, merchants, and businesses. When a provider fails, the ripple effect can disrupt sales proceeds, personal transfers, and inter-institutional payments. The proposed intervention powers aim to prevent such disruptions by allowing CBK to step in early, protect remaining assets, and determine a path forward that minimizes customer loss.
Key concerns include:
- Suspension of payments during statutory management, which could temporarily limit customer access to funds
- Removal of directors and senior officers deemed responsible for a firm's deterioration
- Restrictions on taking on new agents or expanding operations until stability is restored
Key Takeaways
The draft bill represents a significant expansion of CBK's regulatory toolkit, specifically targeting the fintech and payment services sector. By granting the central bank authority to restructure or sell failing providers, the framework seeks to balance investor and operator interests with the protection of end-users.
If enacted, the law would clarify the licensing landscape for fintech startups, closing a legal grey area that has previously allowed commercial banks and telcos to dominate without equivalent oversight.
Conclusion
Kenya's central bank push for intervention powers reflects a broader trend of regulators adapting to the rapid growth of digital finance. The proposed measures could reshape how struggling fintechs are handled, prioritizing customer protection while providing a structured path through financial distress. Stakeholders across the ecosystem from investors to daily users will be watching how the legislation progresses through Parliament.



Discussion
Join the conversation
Thoughtful reactions, questions, and follow-up ideas help shape the next story.