Introduction
Recent unrest in France has drawn global attention, but the underlying pressures driving the streets protests resonate far beyond Paris. From inflation and crumbling schools to record-breaking national debt, the crisis unfolding in France mirrors challenges already familiar to Americans. Examining these parallels reveals how fiscal policy, education investment, and public trust intersect in both nations.
What Happened
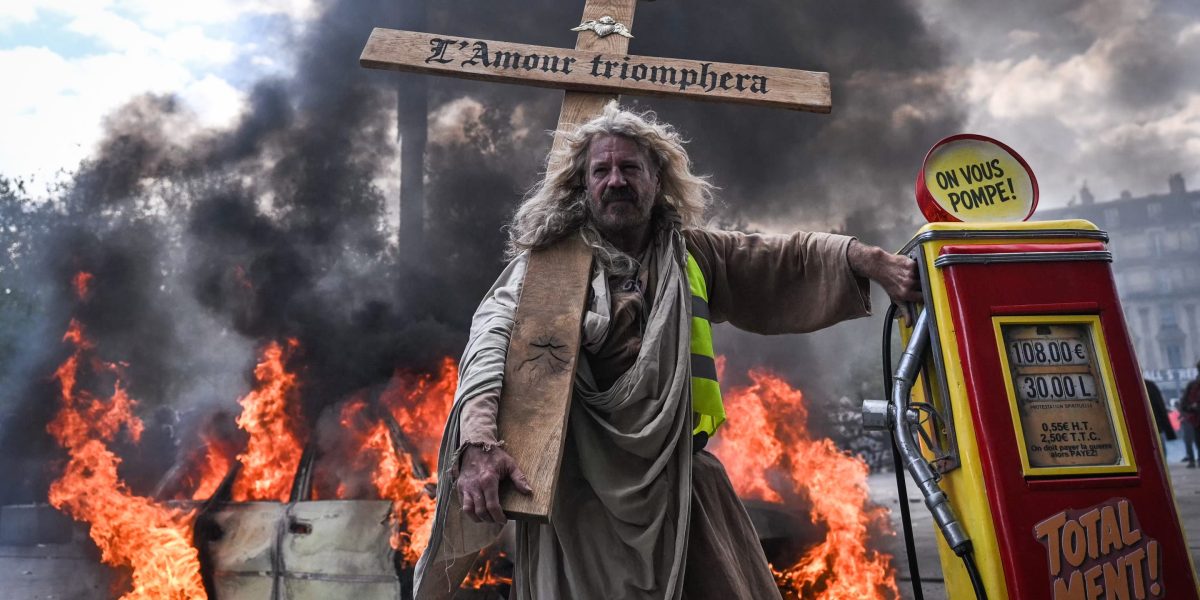
Protests across France began in mid-September when high-school students walked out over missing teachers, overcrowded classrooms, and buildings unable to handle extreme heat. What started as a school-focused demonstration quickly expanded into nationwide unrest, with violent clashes, looting, and hundreds of businesses damaged in Paris, Marseille, and Lyon. Authorities reported over 2,400 arrests in a single day, nearly 1,000 injured police and gendarmes, and widespread property damage. Prime Minister Sébastien Lecornu responded with localized curfews, while Interior Minister Laurent Nuñez admitted police had lost control and offered to resign. President Emmanuel Macron refused to step down, even as the situation highlighted decades of underinvestment in public infrastructure.
Across the Atlantic, American schools face strain of their own. In the 2024–25 school year, 19 percent of U.S. districts canceled classes due to building problems, costing roughly 2 million students about 3.5 million days of learning. Nearly half of all districts reported chronic facility issues disrupting education. Teacher vacancies are rampant: at the start of the 2024–25 year, 74 percent of public schools struggled to fill at least one position with a fully certified instructor, according to federal data. These challenges echo the French experience, where 53 percent of middle and high schools were already missing at least one teacher, and 11.1 percent of secondary educators lacked full qualifications per OECD standards.
Why This Matters
The French riots are not just about immediate price spikes; they are a symptom of a deeper debt dilemma. French public debt has climbed to 119 percent of GDP, while U.S. debt held by the public reached 100.2 percent of GDP by the end of March 2026. Both governments are grappling with deficit reduction, France aiming to cut its shortfall to 5 percent of GDP from 5.4 percent, and Washington facing a $1.992 trillion deficit, or 6.2 percent of GDP, according to Congressional Budget Office projections. Bond markets are treating the two countries as linked: French and U.S. 10-year yields have moved in near lockstep, with analysts warning that cheap debt financing structural deficits becomes dangerous when interest rates rise. Beyond economics, the crisis reflects a growing distrust in institutions. Treasury Secretary Scott Bessent's remarks at Southern Methodist University were followed by the 30-year Treasury yield climbing to 5.69 percent, levels not seen since 2002. Economists caution that without sustainable fiscal consolidation, the risk of a sudden market correction grows. The French situation, where protesters blame years of neglected public services, offers a street-level view of the same tension playing out in bond trading rooms. France's economy is projected to grow just 0.5 percent this year, with youth unemployment near 20 percent, underscoring the human cost of the fiscal strain.
Key Takeaways
- France's unrest and America's hidden school crises share the same root: years of underinvestment in public systems while debt levels climb.
- Both nations face teacher shortages, crumbling facilities, and public frustration when essential services falter.
- Fiscal policy is the common thread: rising deficits, investor anxiety, and the risk of sudden market reactions when cheap debt stops being cheap.
- Policy choices made in the next budget cycle will determine whether these pressures ease or intensify for citizens on both sides of the Atlantic.
Conclusion
The streets of France are burning, but the fire was lit by the same kind of deferred maintenance, unchecked debt, and institutional strain that Americans feel in their own school districts and bank accounts. Recognizing these connections is the first step toward demanding smarter investment and more sustainable fiscal policy. Without it, the risk remains that what starts in a classroom or a town square can quickly become a nationwide and market crisis.





Discussion
Join the conversation
Thoughtful reactions, questions, and follow-up ideas help shape the next story.