Introduction
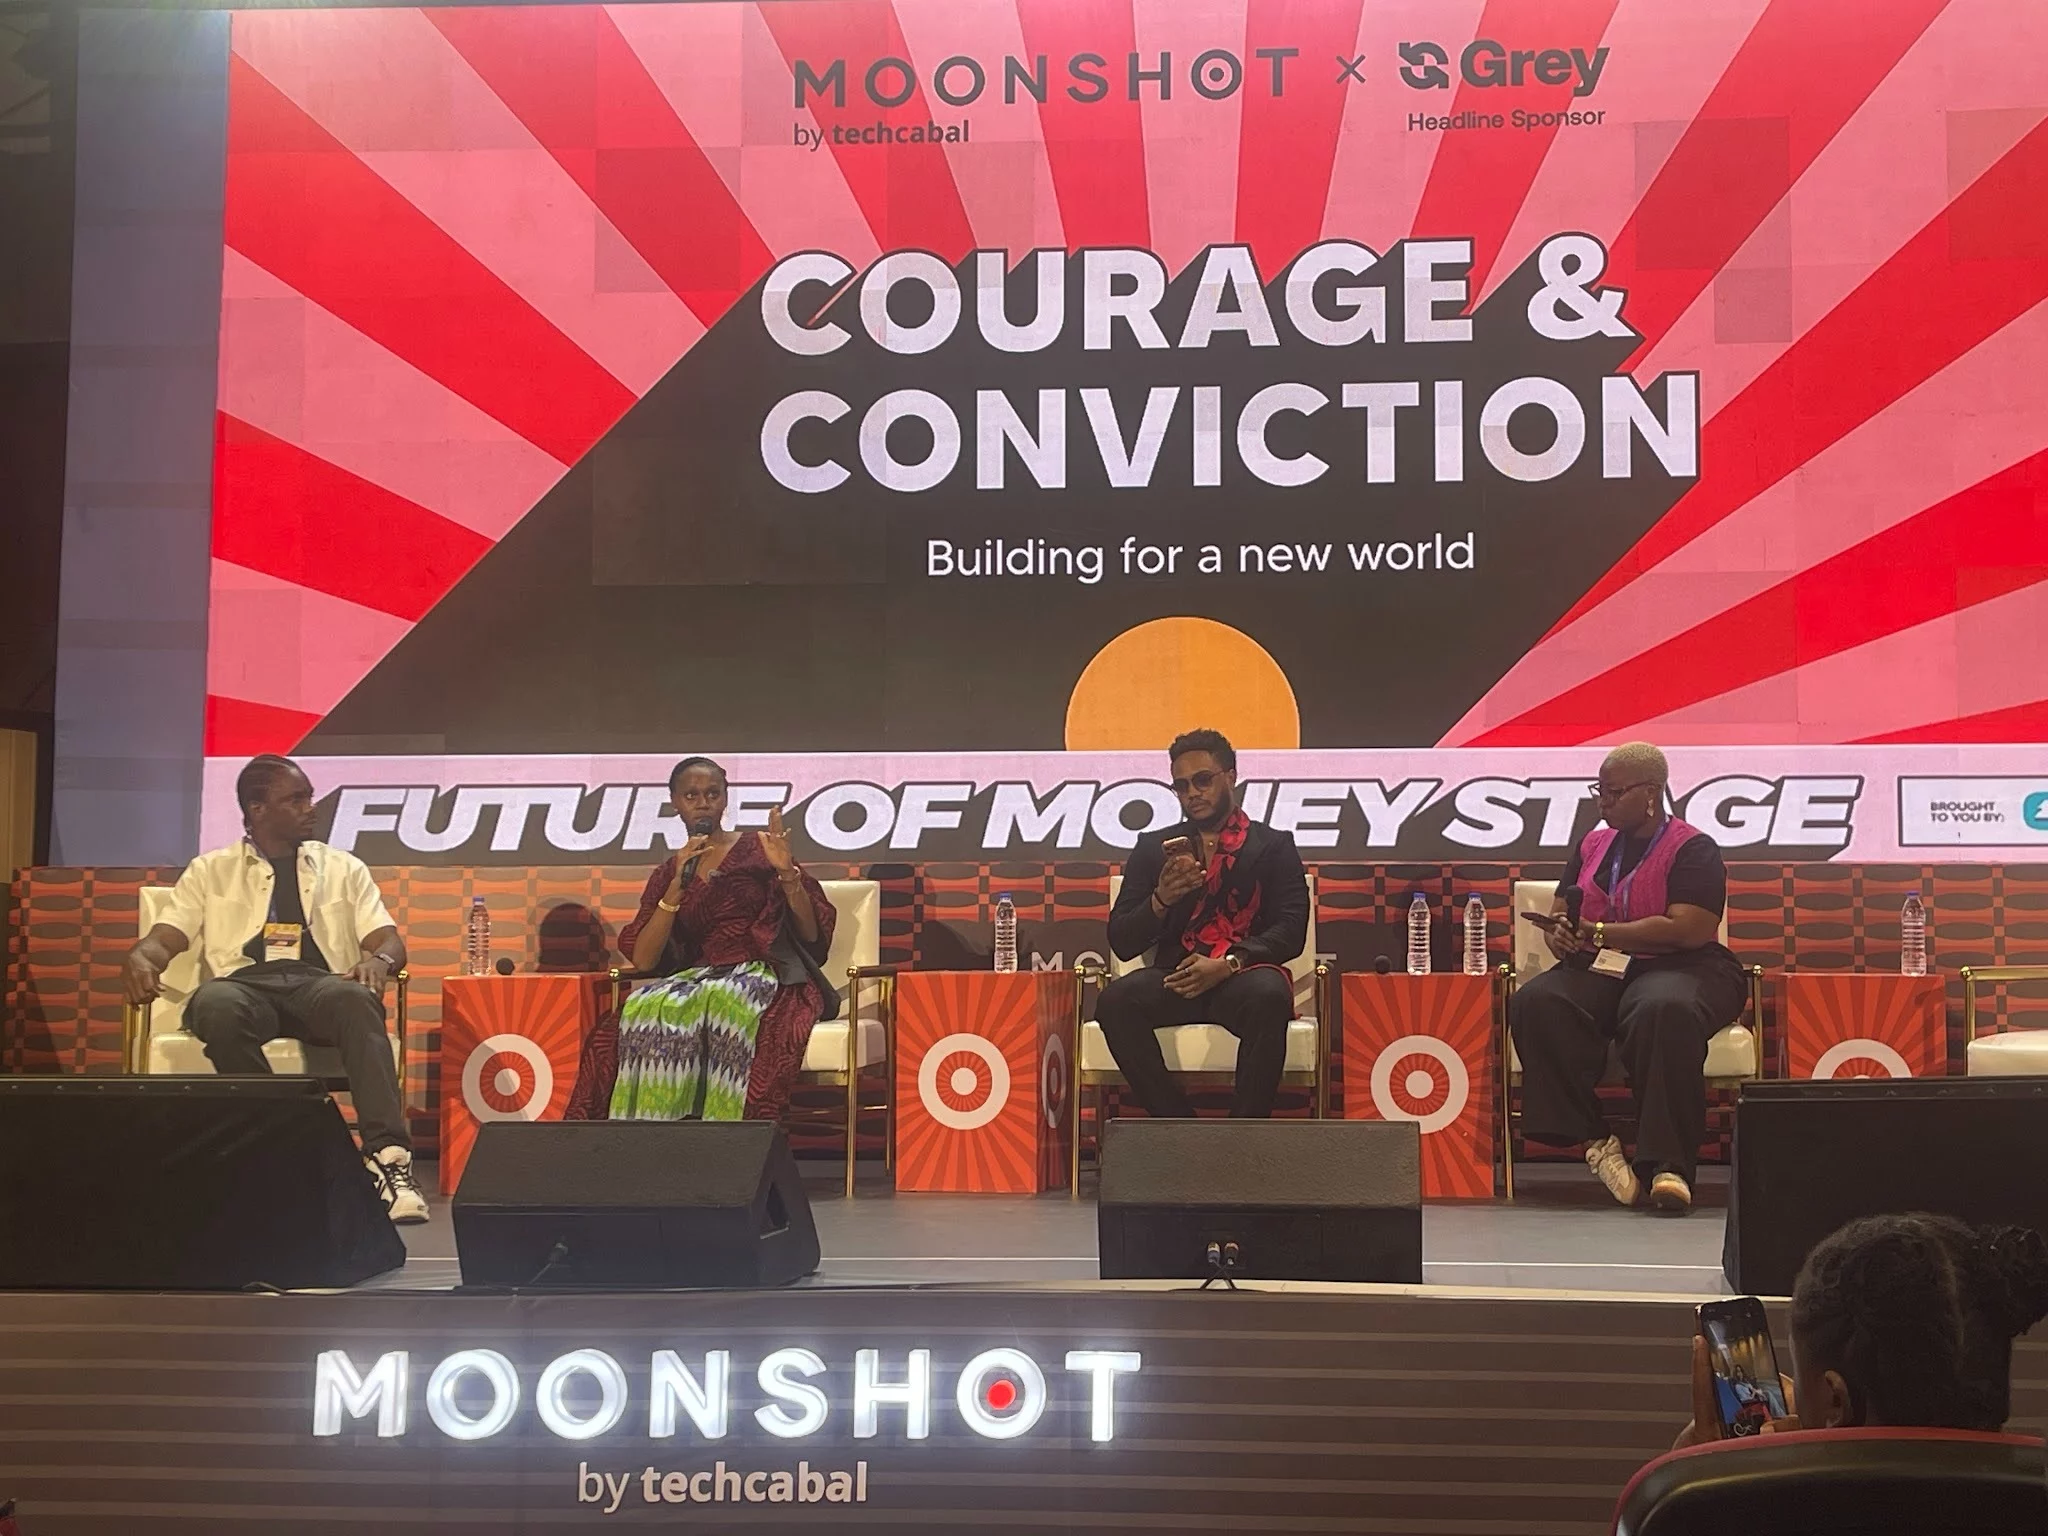
Stablecoins are reshaping how African businesses handle cross-border payments, offering a digital alternative to traditional banking channels. A recent panel at TechCabal's Moonshot conference in Lagos brought together industry leaders to discuss where these digital assets are creating real value and where significant hurdles remain.
What Happened
Representatives from Solana Superteam Nigeria, Obiex and Hyperbridge explained that stablecoins are increasingly used to pay overseas suppliers when dollars are difficult to obtain through conventional banks. Chinonso Obiefule of Solana Superteam Nigeria noted that Nigerian businesses already use stablecoins to settle bills with Chinese suppliers, bypassing the scarcity of physical currency.
Odinaka Esiagu of Obiex highlighted that stablecoins enable payments outside banking hours, allowing companies to transfer funds instantly rather than waiting for the next business day. She emphasized that the technology complements rather than replaces traditional banks.
Seun Lanlege of Hyperbridge pointed to blockchain fragmentation as a key challenge, noting that assets on one network are not always accessible on another. His company built infrastructure to move tokens across ecosystems, prioritising security and decentralisation to avoid centralised single points of failure.
Why This Matters
The impact is reflected in macro data: Nigeria received approximately $59 billion in crypto-asset inflows between July 2023 and June 2024, with the country accounting for roughly 60 per cent of stablecoin inflows into sub-Saharan Africa since 2019. This underscores how deeply stablecoins are integrating into the continent's trade finance ecosystem.
However, adoption faces three persistent barriers. First, transaction costs must become significantly cheaper for stablecoin payments to compete with traditional remittance routes. Second, trust remains a constraint, as past platform hacks continue to deter new users. Third, fragmented blockchain networks limit liquidity flow, making seamless cross-chain transfers difficult without specialised infrastructure.
Key Takeaways
- Cost efficiency is the primary driver: businesses need stablecoin transfers to be cheaper than existing foreign exchange channels.
- Trust and security improvements, including better compliance support, are essential to broaden user confidence.
- Interoperability across blockchains will determine whether stablecoins can truly function as a unified payment layer across Africa.
- Regulatory clarity from bodies like the IMF is expected to shape the framework within which issuers and operators can operate safely.
Conclusion
Stablecoins have moved from niche experiment to practical tool for African traders facing currency access challenges. While costs, security perceptions and network fragmentation remain obstacles, ongoing infrastructure projects and regulatory dialogue are laying the groundwork for broader integration. The coming years will likely determine whether stablecoins become a mainstream financial layer or remain a niche alternative for specific use cases.



Discussion
Join the conversation
Thoughtful reactions, questions, and follow-up ideas help shape the next story.